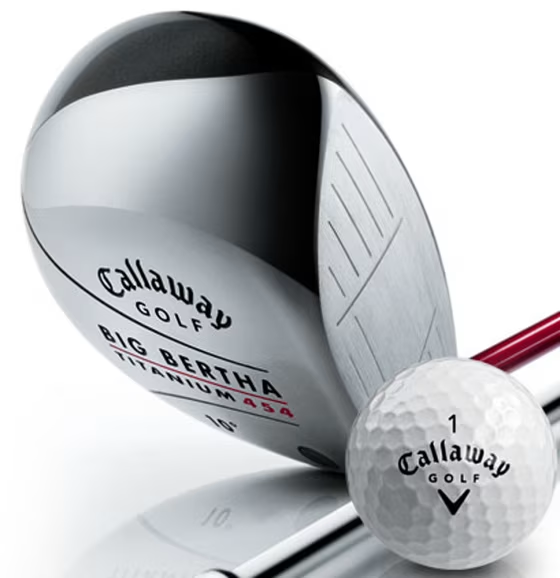
Callaway Golf Co. on Thursday said it has received unsolicited indications of interest from various parties, but no firm offers have been made.
The comments came on a day when shares of the company rose 13 percent on speculation the struggling golf club maker was planning to go private.
According to a report in Thursday's Los Angeles Times, Callaway is quietly weighing an all-cash, $1.2-billion takeover bid that would take the nation’s largest manufacturer of golf clubs private.
 FOR SUBSCRIBERSA harrowing ordeal aboard an Israel-bound plane
FOR SUBSCRIBERSThe debate over AI’s future rages on both coasts
The unsolicited takeover offer from buyout firm Thomas H. Lee Partners and insurance mogul William Foley II was submitted to Callaway’s board May 20, sources close to the situation told The Los Angeles Times.
During a meeting Monday of a board committee formed to review the offer, Callaway’s top executive team unanimously endorsed the bid, according to the newspaper. Leading that effort was Callaway Chairman William Baker, 71, a board member since 1994 who has been serving as chief executive since a management shake-up in August.
FOR SUBSCRIBERSA harrowing ordeal aboard an Israel-bound plane
FOR SUBSCRIBERSThe debate over AI’s future rages on both coasts
The Times reported that the board is said to be divided over the offer, with some campaigning to oust Baker as CEO in favor of Anthony Thornley, who joined the board last year and is angling to get Baker’s job after being passed over in March to run Qualcomm Inc., the San Diego-based wireless equipment company from which he is due to step down as president July 1.
The paper reported that phone calls to Baker, Thornley and Ronald Beard, Callaway’s lead independent director, were not returned Wednesday. Foley and representatives from Thomas Lee also did not respond to requests for comment.