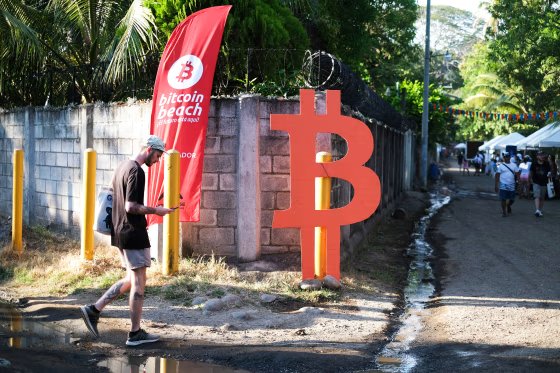
Bitcoin slumped below $27,000 Thursday for the first time in over 16 months, as cryptocurrency markets extended their losses amid fears over rising inflation and the collapse of a controversial stablecoin project.
The price of bitcoin plunged as low as $26,595.52 Thursday morning, according to Bitstamp data. That marks the first time bitcoin has sunk below the $27,000 level since Dec. 30, 2020.
As of 1:30 a.m. ET, bitcoin was trading at $27,061, down 15 percent in the last 24 hours.
Ether, the second-biggest digital currency, tanked to as low as $1,789 per coin. It’s the first time the token has fallen beneath the $2,000 mark since July 2021.
Ether was last down 23 percent at a price of $1,852.
Investors are fleeing from cryptocurrencies at a time when stock markets have plunged from the highs of the coronavirus pandemic on fears over soaring prices and a deteriorating economic outlook.
U.S. inflation data out Wednesday showed prices for goods and services jumping 8.3 percent in April, higher than expected by analysts and close to the highest level in 40 years.
Also weighing on traders’ minds is the downfall of embattled stablecoin protocol Terra.
TerraUSD, or UST, is supposed to mirror the value of the dollar, but it plummeted to less than 30 cents Wednesday, shaking investors’ confidence in the so-called decentralized finance space.
Stablecoins are like the bank accounts of the barely regulated crypto world. Digital currency investors often turn to them for safety in times of volatility in the markets.

But UST, an “algorithmic” stablecoin that’s underpinned by code rather than cash held in a reserve, has struggled to maintain a stable value as holders have bolted for the exit en masse.
As of Thursday morning, UST was trading at about 62 cents, still well below its intended $1 peg.
Luna, another Terra token that has a floating price and is meant to absorb UST price shocks, erased 97 percent of its value in 24 hours and was last worth just 30 cents — even less than UST.
Investors are scared about the implications for bitcoin. Luna Foundation Guard — a fund set up by Terra creator Do Kwon — had amassed a multibillion-dollar pile of bitcoin to help support UST in times of crisis.
The fear is that Luna Foundation Guard will sell a large portion of its bitcoin holdings to shore up its ailing stablecoin. That’s a risky gamble, not least because bitcoin is itself an incredibly volatile asset.
Adding to investors’ fears Thursday was a drop in the value of tether, the world’s biggest stablecoin. The token at one point slipped below 99 cents. Economists have long feared that tether may not have the required amount of reserves to bolster its dollar peg in the event of mass withdrawals.